Hey there! Ever wondered how much auto insurance costs in Massachusetts? Whether you’re cruising down the historic streets of Boston or exploring the scenic Berkshires, understanding your insurance options is crucial. Let’s break it down so you can hit the road with confidence.
In Massachusetts, auto insurance isn’t just a legal requirement—it’s your safety net against the unexpected. From the essential basics to savvy saving strategies, we’ve got the scoop on everything you need to know. Ready to dive in? Keep reading!
Understanding Auto Insurance Basics in Massachusetts
Did you know that every driver in Massachusetts is legally required to have auto insurance? It’s not just about staying on the right side of the law; it’s about protecting you and your investment.
Auto insurance in Massachusetts might seem complex at first. But once you get a handle on the basics, it’s smooth sailing. Let’s break it down into easy-to-understand components.
Key Components of Auto Insurance Coverage in Massachusetts
The state of Massachusetts has specific requirements when it comes to auto insurance. There are four key components you need to be aware of. Each plays a crucial role in how you’re covered in the event of an accident.
Bodily Injury Liability covers injuries you cause to others. If you’re at fault in an accident, this takes care of the other party’s medical expenses. Property Damage Liability covers damage to others’ property. It steps in if you hit a car or damage someone’s fence.
Minimum Insurance Requirements Set by the State
Alright, let’s talk numbers. The minimum coverage requirements in Massachusetts are set to ensure that you’re protected without breaking the bank. Here’s what you need to know:
- $20,000 per person for bodily injury
- $40,000 per accident for bodily injury
- $5,000 for property damage
- $8,000 for Personal Injury Protection (PIP)
Here is the deal: These are the minimums. You might want to consider more coverage for better protection.
Difference Between Liability, Collision, and Comprehensive Coverage
Understanding the differences in coverage types can save you a headache — and some cash. Here’s a quick breakdown:
- Liability Coverage: Covers others when the accident is your fault.
- Collision Coverage: Pays for damage to your car resulting from a collision.
- Comprehensive Coverage: Covers damage to your car not involving a collision (think theft or natural disasters).
Pro Tip: While comprehensive coverage is optional, it’s a smart choice if you want peace of mind against the unexpected.
Factors Influencing Auto Insurance Costs
Ever wondered why your auto insurance premium is through the roof? It’s not just random. There’s a method to the madness!
Auto insurance rates in Massachusetts hinge on a variety of factors. Age, driving history, and vehicle type are just the tip of the iceberg.
Key Components That Shape Your Premium
Let’s break down the core factors that can send your insurance costs soaring or plummeting. From your driving record to your car’s make and model, everything counts.
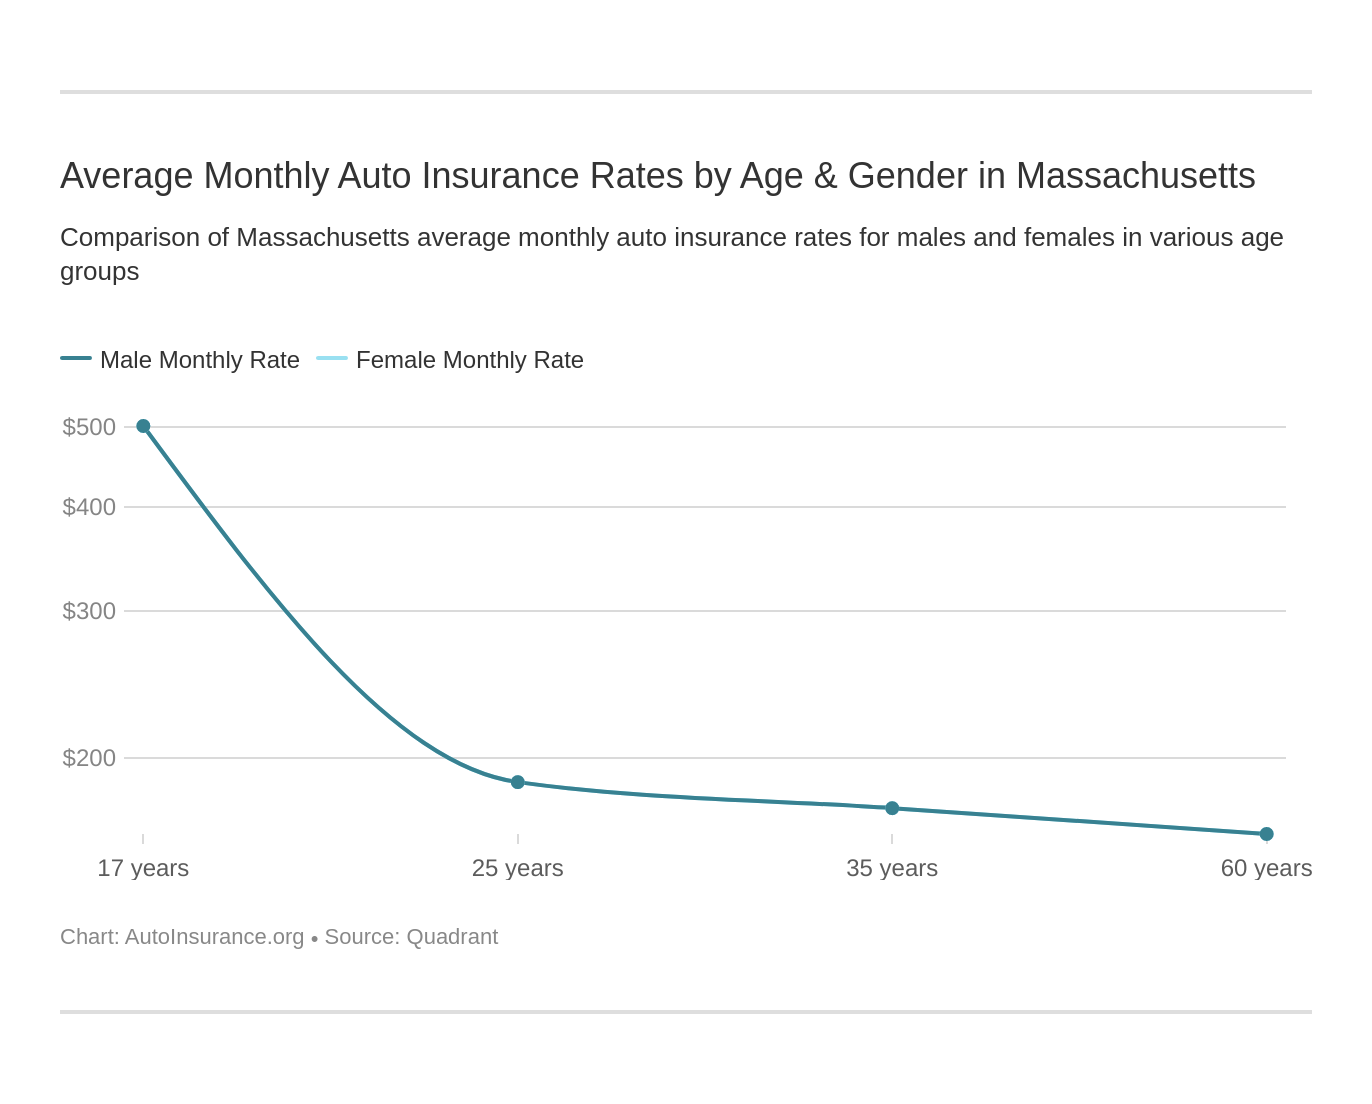
- Your age and gender play a significant role; younger drivers usually pay more.
- Where you live also impacts costs due to varying levels of traffic and crime.
- Your driving history, including accidents and tickets, heavily influences your rates.
- The type of vehicle you drive—sports cars and luxury vehicles cost more to insure.
Driving History and Vehicle Type: The Game Changers
Your driving history is like your insurance report card. A clean record? That’s gold. BUT a single speeding ticket, and you can watch your rates skyrocket. It’s that simple!
Then there’s your vehicle type. Insuring a minivan? Cheaper. A brand-new sports car? Expect a premium price tag. Here’s the deal: insurers see flashy cars as higher risks. And trust me, they charge accordingly.
| Factor | Description | Impact on Cost |
|---|---|---|
| Age | Older drivers generally pay less. | High for young drivers, lower for older drivers. |
| Driving History | Accidents and tickets increase rates. | Clean records get better rates. |
| Vehicle Type | Sports cars and luxury models cost more to insure. | Basic models = lower cost, expensive models = higher cost. |
Pro Tip: Want to cut costs? Maintain a clean driving record and choose a vehicle that’s less of a target for theft or accidents.
Average Auto Insurance Rates in Massachusetts
How much do you really need to pay for auto insurance in Massachusetts? You might be surprised to learn that the average cost can vary significantly depending on several factors.
In Massachusetts, the average cost of auto insurance isn’t just a flat number. The type of coverage you choose plays a massive role in determining how much you shell out each year. Let’s break it down.
Breaking Down the Average Costs
Here’s the deal: the type of coverage you opt for can drastically change your annual premium. Whether you’re going for basic liability or a comprehensive package, each has its own price tag.
| Coverage Type | Average Cost | Description |
|---|---|---|
| Liability Only | $600 | Covers damages to others in accidents you’re found liable for. |
| Collision Coverage | $1,200 | Protects your vehicle in the event of a collision, regardless of fault. |
| Comprehensive Coverage | $1,500 | Covers non-collision-related incidents such as theft or natural disasters. |
Location Matters
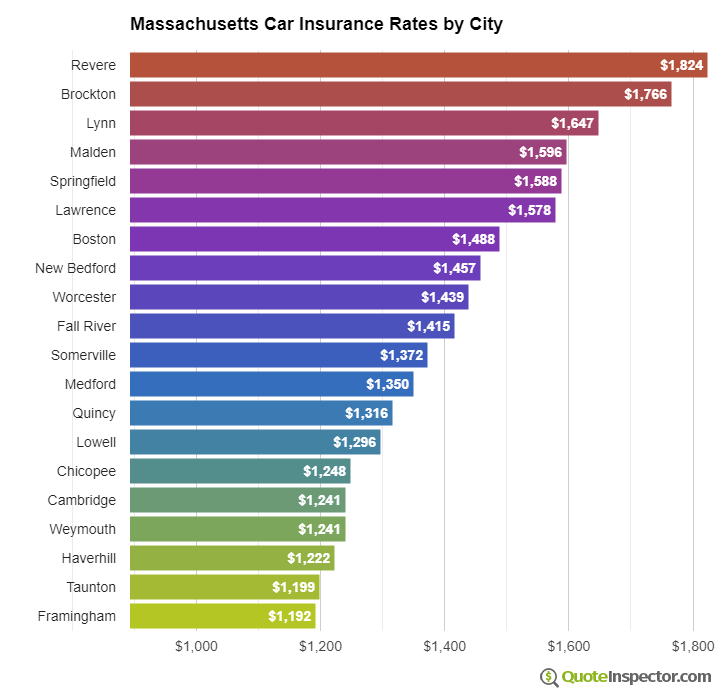
Now, what if I told you that where you live in Massachusetts could make or break your insurance premium? It’s true. For instance, if you’re in a bustling city like Boston, expect rates to soar compared to a quieter town like Amherst.
Areas with higher traffic density tend to have more claims, which means higher premiums for you. But in less populated areas, insurers view you as a lower risk.
Pro Tip: Consider your location when budgeting for auto insurance. If you’re planning a move, research the impact on your premiums beforehand.
Saving Money on Auto Insurance
Did you know that the average American spends over $1,000 a year on auto insurance? That’s a hefty chunk of change! But, there are sneaky strategies you can use to slash those premiums in Massachusetts.
Insurance isn’t a “set it and forget it” deal. With a little effort, you can find ways to save big. Let’s dive into the ways you can keep more money in your wallet without sacrificing coverage.
Effective Strategies to Reduce Premiums
Here’s the deal: auto insurance premiums aren’t set in stone. You can often negotiate better rates or find ways to reduce costs. One simple strategy? Increase your deductible. It might sound scary, but raising your deductible can significantly lower your monthly premium. Of course, you’ll need to have some cash set aside in case you need to file a claim.
Pro Tip: Always shop around. Different insurers offer different rates, and competition is fierce.
Another tactic is to maintain a clean driving record. This means no tickets or accidents. Insurers see you as less risky, which often leads to lower premiums.
Discounts Offered by Insurers
Insurers in Massachusetts offer a variety of discounts that can help you save. Here’s a list of some popular ones:
- Multi-Policy Discount: Bundle your auto and home insurance for a discount.
- Safe Driver Discount: No accidents or tickets? You could save big.
- Good Student Discount: If your kid has a solid GPA, you might qualify.
- Anti-Theft Discount: Cars with anti-theft devices can secure lower rates.
- Low Mileage Discount: Drive less? Pay less. Simple as that.
Take advantage of these discounts. They can add up to significant savings on your premium.
Benefits of Bundling Auto Insurance
Bundling isn’t just for cable and internet. You can also bundle your insurance policies to save money. By combining your auto insurance with other types of insurance—like home or renters insurance—you can often snag a sweet discount. Plus, it makes managing your policies simpler.
But, here’s the kicker: not all bundles are created equal. You need to compare the bundled rate with individual policy rates to ensure you’re actually getting a deal.
Pro Tip: Ask your insurance provider about bundling options, but always do the math.
By taking these steps, you not only save money but also streamline your insurance experience.
Comparing Auto Insurance Providers
Ever wondered how different auto insurance providers stack up in Massachusetts? Choosing the right provider can save you hundreds each year!
When it comes to auto insurance, not all providers are created equal. Some offer better rates, while others provide superior customer service or unique features like roadside assistance. But, how do you find the one that’s right for you? Here is the deal: you need a clear comparison to make an informed decision.
Major Auto Insurance Providers in Massachusetts
Let’s dive into a comparison of some major players in Massachusetts. Below is a table that highlights different aspects like key features, average rates, and customer ratings. Check it out:
| Provider | Key Features | Average Rates | Customer Ratings |
|---|---|---|---|
| Geico | Low rates, online service | $1,200/yr | 4.5/5 |
| Progressive | Customizable policies, discounts | $1,400/yr | 4/5 |
| State Farm | Local agents, comprehensive coverage | $1,350/yr | 4.2/5 |
| Allstate | Accident forgiveness, mobile app | $1,500/yr | 4.1/5 |
Reading customer reviews and ratings is crucial when comparing providers. Why? Because they reveal the true experiences of other customers. You can spot trends in customer service, claim processing, and even hidden fees that aren’t evident in slick marketing campaigns.
Pro Tip: Before you commit, spend time reading online reviews to ensure you’re getting the best value for your money.
Legal and Regulatory Considerations
Did you know that driving without insurance in Massachusetts can lead to fines, license suspension, and even jail time? It’s crucial to understand the legal landscape before hitting the road.
Massachusetts mandates specific auto insurance requirements. And if you’re not in compliance, the consequences can be severe. Let’s dive into the nitty-gritty of what you need to keep you and your car legal.
Massachusetts Auto Insurance Requirements
Here’s the deal: Massachusetts is one of the states with a compulsory auto insurance system. This means you can’t legally drive without meeting the minimum coverage requirements. The state requires every driver to have:
- Bodily Injury to Others: $20,000 per person / $40,000 per accident
- Personal Injury Protection (PIP): $8,000 per person
- Bodily Injury Caused by an Uninsured Auto: $20,000 per person / $40,000 per accident
- Property Damage: $5,000 per accident
These might seem like just numbers, BUT skipping coverage could cost you way more in fines and penalties.
Penalties for Non-Compliance
If you’re caught without the required insurance, the penalties are not just a slap on the wrist. We’re talking about fines up to $5,000, license suspension, and even possible jail time. That’s serious money and hassle just for skipping insurance.
Massachusetts takes its insurance laws seriously, and so should you. Make sure you have the mandatory coverage to avoid these costly penalties.
Recent Changes in Massachusetts Insurance Laws
Insurance laws aren’t static. They change, and you need to keep up. Recently, Massachusetts updated its laws to include stricter penalties for repeat offenders and increased minimum coverage limits.
Pro Tip:
Stay informed about legislative updates by subscribing to insurance law alerts or newsletters. This can save you from unexpected fines or changes in your premiums.
By staying on top of these changes, you ensure you’re always compliant. Don’t let a lack of information cost you your driving privileges.
Closure
And there you have it! Navigating the world of auto insurance in Massachusetts doesn’t have to feel like driving through a maze. With the right knowledge and strategies, you can secure the coverage you need at a price that won’t break the bank. Drive safe and smart—your journey to the perfect policy starts here!
Answers to Common Questions
How much is the average auto insurance cost in Massachusetts?
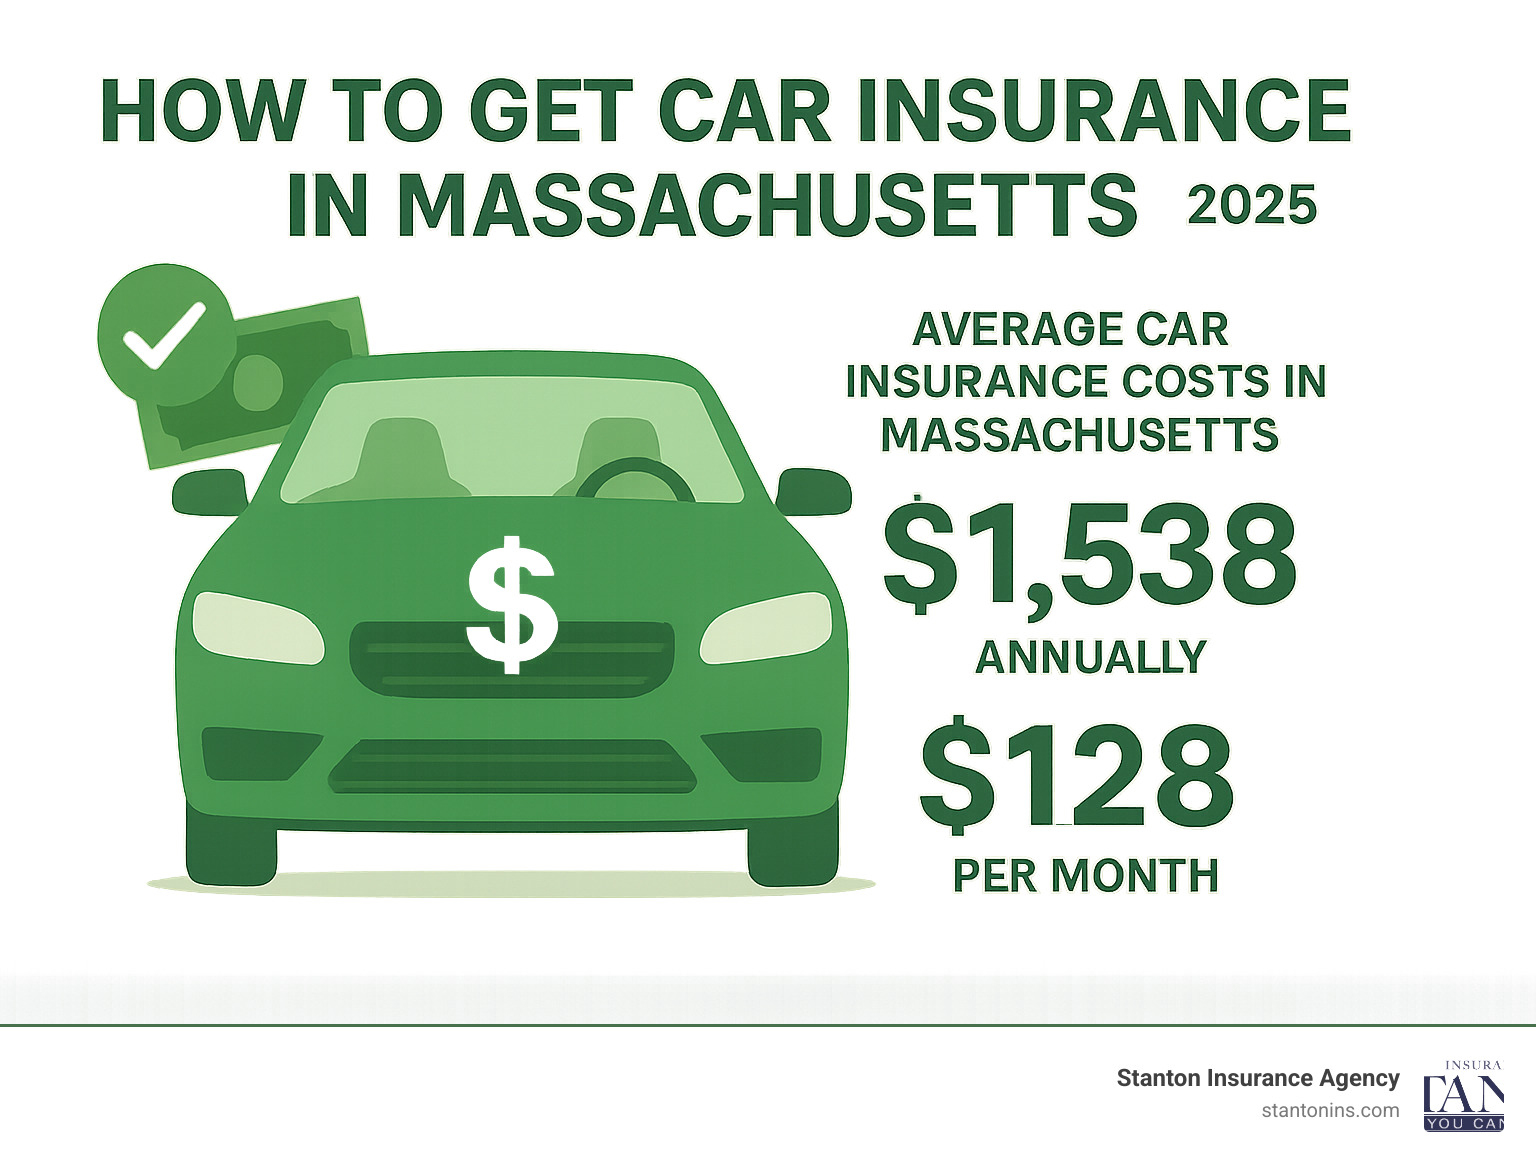
The average cost varies, but typically it hovers around $1,200 to $1,500 annually, depending on coverage and personal factors.
What are the minimum auto insurance requirements in Massachusetts?
The state requires a minimum of $20,000 per person and $40,000 per accident for bodily injury, and $5,000 for property damage.
How can I reduce my auto insurance premiums in Massachusetts?
Consider bundling policies, maintaining a clean driving record, and taking advantage of discounts for things like low mileage and good student performance.
Does my location affect my auto insurance rates in Massachusetts?
Yes, rates can vary significantly by location due to factors like traffic density, crime rates, and accident statistics.
What are the penalties for driving without insurance in Massachusetts?
Penalties include fines, license suspension, and increased premiums once coverage is obtained.
How does my driving history impact my insurance rates?
A clean driving record can lower premiums, while accidents and violations typically increase costs.
